
🏠 Wealth or LUXURY tax in 2027: what changes for owners of homes worth over 4 million lei?
TOT Capital Analysis | Real Estate, Investments and Capital
Starting with fiscal year 2027, the tax policy proposed by the authorities provides for an important change in the way wealth tax is applied in the Republic of Moldova.
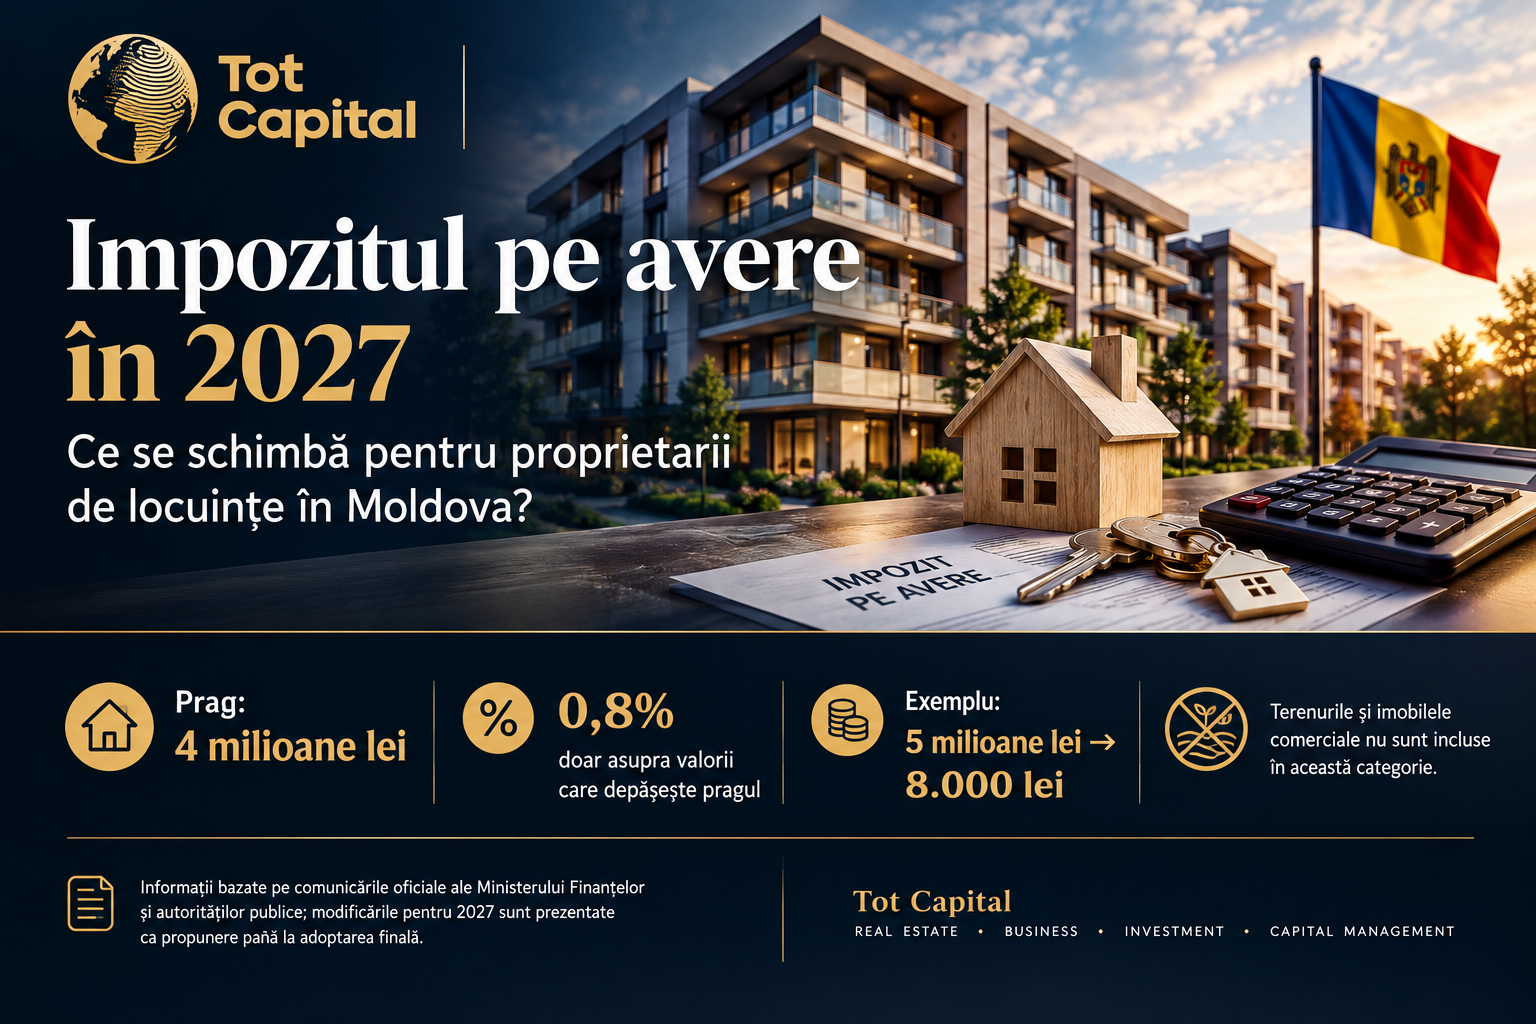
One of the main changes is the introduction of a threshold of 4 million lei for the estimated value of residential real estate. According to the Ministry of Finance, the 0.8% rate will apply only to the value exceeding the threshold of 4 million lei.
Ordinary tax on real estate According to the law, the rate of this tax must fall within the limits of a minimum of 0.05% and a maximum of 0.3% of the cadastral value of the property.
What properties are targeted?
The measure refers to residential real estate, including:
apartments;
residential houses;
holiday homes.
Important: the wealth tax regime covers these residential properties and excludes land. The State Tax Service specifies in its tax practice that the subjects of wealth tax are individuals who own residential real estate, including holiday homes, "with the exception of land".
Therefore, agricultural land, construction land or land for other purposes do not fall into this wealth tax category simply because they have a high value.
Likewise, real estate with a purpose other than residential, such as commercial spaces or certain industrial properties, are regulated by the real estate tax regime, not by this wealth tax rule.
💰 How does the 4 million lei threshold work?
Here is one of the most important differences from a simple interpretation of the 0.8% quote.
According to the proposal for 2027, 0.8% is not applied to the entire value of the home, but to the part that exceeds 4 million lei. The Ministry of Finance explicitly provides this wording in the presentation of the fiscal policy for 2027.
Example 1 – home valued at 4 million lei
Value:
4,000,000 lei
The part that exceeds the threshold:
0 lei
The additional tax calculated according to the 0.8% mechanism:
0 lei
Example 2 – home valued at 5 million lei
Value:
5,000,000 lei
Threshold:
4,000,000 lei
Difference:
1,000,000 lei
Calculation:
1,000,000 × 0.8% = 8,000 lei
So, in the simplified example, the wealth tax related to the proposed mechanism would be 8,000 lei.
Example 3 – home valued at 10 million lei
Value:
10,000,000 lei
The part that exceeds the threshold:
6,000,000 lei
Calculation:
6,000,000 × 0.8% = 48,000 lei
⚠️ Cadastral value or contractual value?
An important clarification is necessary here.
In the matter of wealth tax, the base is linked to the estimated value of the assets, established according to fiscal/cadastral rules. The State Tax Service indicates that the taxable base is the estimated value of the assets, assessed by the cadastral bodies.
In addition, the Agency for Geodesy, Cartography and Cadastre announced that the new values resulting from the massive evaluation and revaluation are to be applied starting January 1, 2027, after the completion of the stages provided for by the process.
Therefore, for homeowners, the estimated/cadastral value used for tax purposes is important, not simply the price the owner would declare in a contract.
🌳 What about the land?
This is where an important difference arises for investors.
The land is not subject to wealth tax just because it has a value of over 4 million lei.
For example:
Agricultural land
Value: 6 million lei
→ does not automatically become subject to the 0.8% wealth tax just because of the value.
Land for construction
Value: 8 million lei
→ does not fall under the 0.8% wealth tax mechanism for housing.
Commercial space
Value: 10 million lei
→ does not fall under this wealth tax rule for residential property.
For these categories, the tax regime corresponding to the destination of the real estate property applies, including the rules regarding the tax on real estate. The SFS explicitly differentiates between residential property, agricultural land and property with another destination.
🏢 What does it mean for real estate investors?
For investors, the difference between:
apartment / house
and
land / commercial space / industrial property
becomes important when calculating the annual cost of holding a portfolio.
When evaluating a real estate investment, it is not enough to only analyze:
purchase price → rent → yield.
The following should also be analyzed:
real estate tax;
wealth tax, if applicable;
administration costs;
maintenance;
insurance;
financing;
transaction costs;
the tax regime of rental income;
any changes in cadastral values.
TOT Capital recommends that the tax analysis be done together with the legal and investment analysis of the property.
📊 Simplified example for a portfolio
Let's assume that an individual owns:
Property Value
Apartment 5 million lei
House 7 million lei
Agricultural land 6 million lei
Commercial space 8 million lei
In the proposed wealth tax mechanism, we do not automatically add up all 26 million lei and apply 0.8% on the difference.
The rule discussed for 2027 concerns residential real estate, including vacation homes, and land is excluded.
📅 When is it paid?
The payment deadline must be checked after the changes for 2027 and the rules applicable to that year come into force, as a general deadline is March, April.
🔎 What to watch for in 2027?
For real estate owners and investors, three elements will be important:
1. Fiscal/cadastral value of the property
The new cadastral values are to be used from 2027, after the completion of the revaluation process.
2. Legal destination of the property
Residential, agricultural, commercial, industrial, etc.
3. Value exceeding the threshold of 4 million lei
In the 2027 proposal, the 0.8% quota is applied only to the part exceeding the threshold.
TOT Capital: the investor's perspective
In the real estate market, the difference between market value, contractual value, and the value used for tax purposes is essential.
Before purchasing a high-value property, the investor must analyze not only the potential for capital appreciation, but also the tax and operational cost of long-term ownership.
For 2027, owners of high-value homes will have to pay particular attention to the application of the new threshold of 4 million lei and the 0.8% rate on the excess value, if the amendments are adopted in the proposed form.
TOT Capital
Real Estate • Business • Investment • Capital Management
Official sources
Ministry of Finance – Fiscal and customs policy for 2027
https://mf.gov.md/ro/content/politica-fiscal%C4%83-%C8%99i-vamal%C4%83-pentru-anul-2027-aprobat%C4%83-de-guvern?language=ro&utm_source=chatgpt.com
Government of the Republic of Moldova – Fiscal and customs policy for 2027
State Tax Service – Wealth tax subjects
https://www.sfs.md/uploads/files/codul%20fiscal/PARLAMENTUL%20REPUBLICII%20MOLDOVA.pdf?utm_source=chatgpt.com
State Tax Service – The object of wealth tax
Geodesy, Cartography and Cadastre Agency – clarifications regarding the revaluation of real estate
https://agcc.gov.md/content/clarific%C4%83ri-privind-impactul-fiscal-al-actualiz%C4%83rii-valorilor-bunurilor-imobile?utm_source=chatgpt.com